Cycle of September 29, 2026 · Radar xTech · Brazil · Public edition
This cycle’s reading
The pace of energy and digital-infrastructure business in Brazil is being set by the power grid, contracted energy and regulatory compliance, not by interest rates. Treating the expected fall in Brazil’s policy rate as relief already secured is the biggest risk of the cycle.
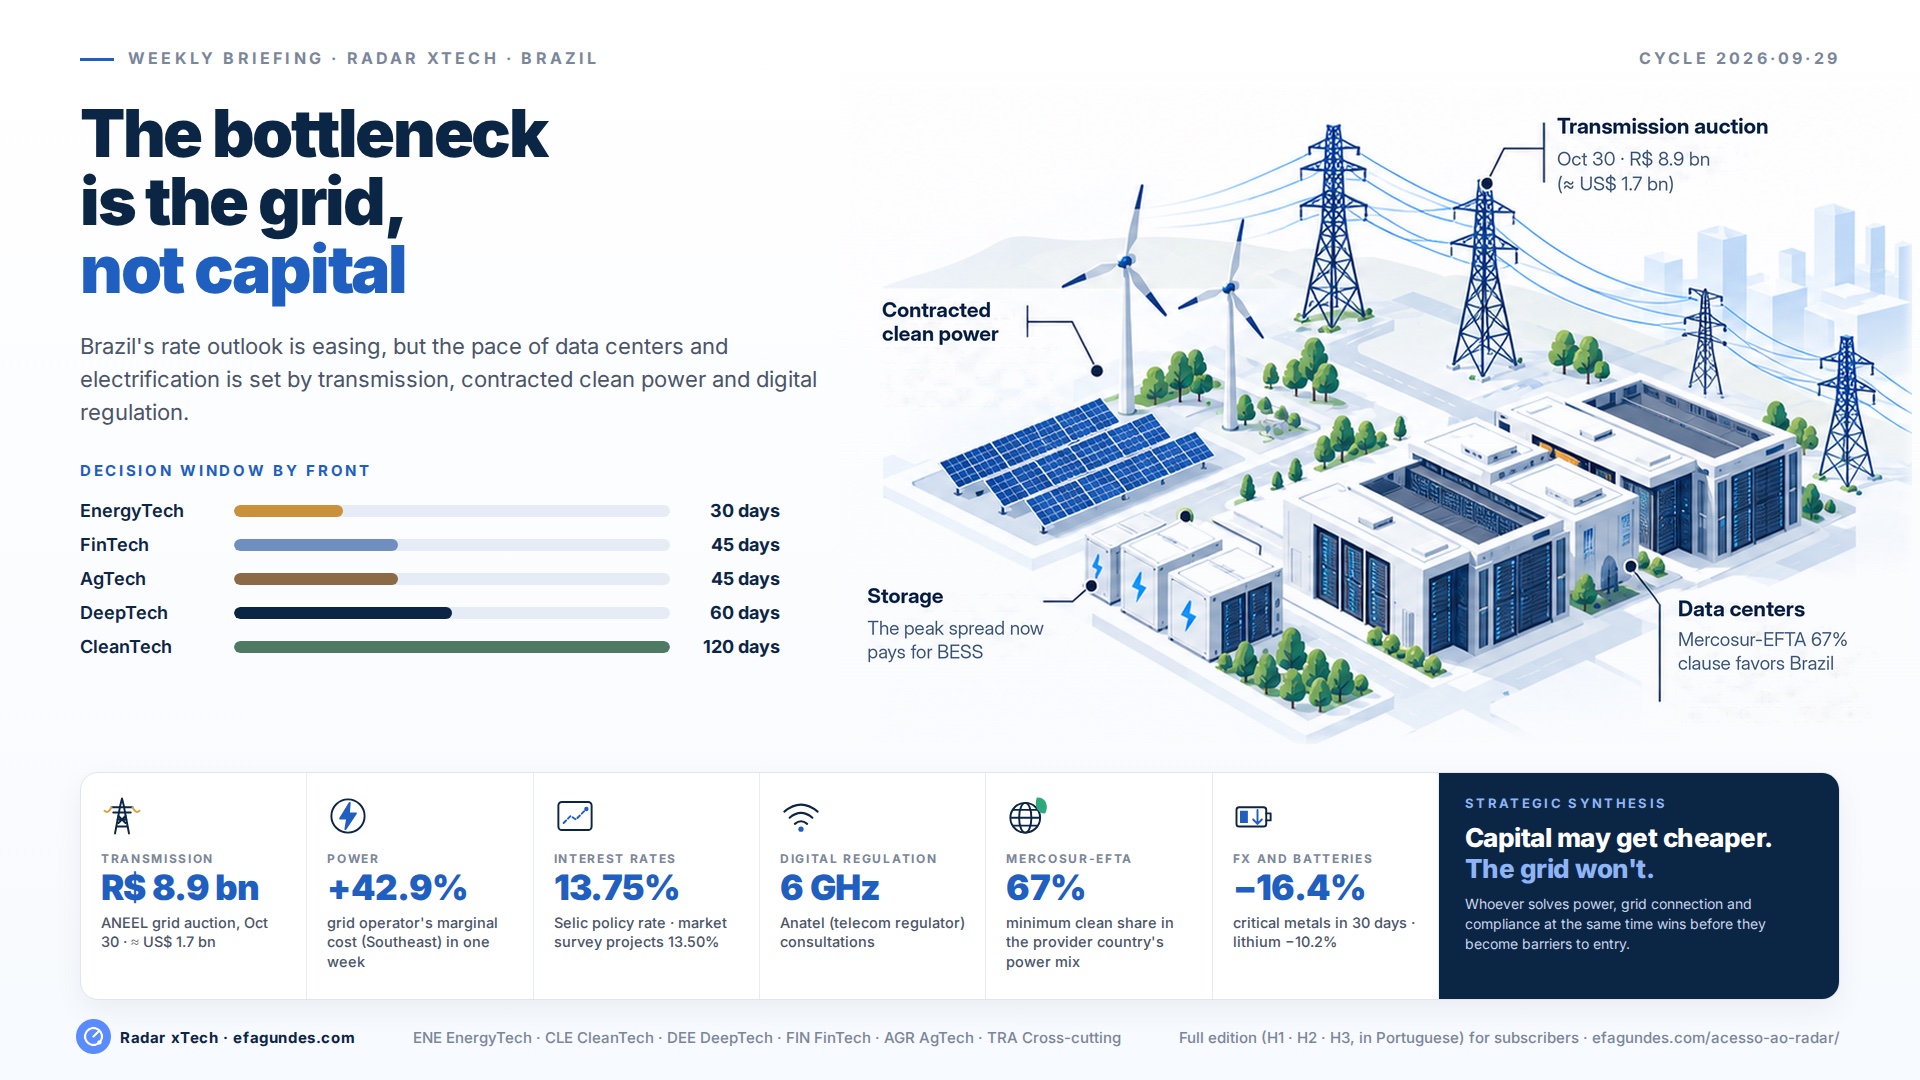
Brazil’s interest-rate outlook is easing, but the pace of data centers and electrification is set by transmission, contracted clean power and digital regulation.
Power gets more expensive in the short term. The grid operator’s marginal operating cost for Brazil’s Southeast/Center-West region rose 42.9% in one week (R$ 68.52 to R$ 97.89/MWh, about US$ 13 to US$ 19), with a “yellow” tariff surcharge in force and Brent up 6.3% in 30 days. This hits energy bills and free-market power purchases.
ENETRA
Opportunity
Contracted power and storage gain value. The spread between midday solar and the evening peak is widening, and data centers compete for firm power. The 67% clean-energy clause in the Mercosur-EFTA trade agreement, in force with Iceland from October 1, favors providers operating on Brazil’s largely renewable grid. Power purchase agreements, battery storage and efficiency find demand.
ENECLEDEE
Risk
Rates: the cut is a forecast, not a contract. The policy rate (Selic) stands at 13.75% and the real rate at 9.53% a year. The central bank’s market survey projects 13.50% by year-end, but banks still price corporate credit in double digits. Plans that assume relief put cash at risk; the useful window is to renegotiate terms and covenants.
FINTRA
Opportunity
R$ 8.9 billion transmission auction on October 30. The auction (about US$ 1.7 billion in capex) mobilizes equipment suppliers, engineering, construction and finance, and will decide where grid connection capacity for data centers exists over the next decade. The decision to bid falls due in early October.
ENEDEE
Risk
Currency and equipment lead times. The dollar at R$ 5.21 offers a respite, but servers, GPUs and equipment with delivery beyond 120 days need hedging. In the opposite direction, battery-chain metals fell over 30 days (lithium −10.2%, critical metals −16.4%).
CLEDEETRA
Mixed
Digital regulation speeds up. On September 25 the telecom regulator (Anatel) opened two public consultations on outdoor Wi-Fi in the 6 GHz band, with 70 days for input, and an illegal-betting block involves some 20,000 internet providers and restrictions on Pix, Brazil’s instant-payment system. Compliance becomes a fixed cost, and also a service to sell.
DEEFIN
Risk
Counterparty risk in telecoms. The bankruptcy of Oi, a legacy Brazilian telecom operator, is expected to involve more than 180,000 creditors. Suppliers, customers and companies relying on its connectivity need to measure exposure and plan contingencies.
DEETRA
Mixed
Agriculture: tight margins, fast-payback technology. Squeezed grain margins and fertilizer supply pressure push farmers from heavy machinery toward efficiency that pays back in one harvest: soil sensors, targeted spraying, biological inputs.
AGR
ENE EnergyTech · CLE CleanTech · DEE DeepTech · FIN FinTech · AGR AgTech · TRA Cross-cutting (affects any operation)
The numbers that enter the decision
USD/BRLR$ 5.21−0.8% in the cycle · cost of imported capex
Real Selic9.53% p.a.Selic minus 12-month IPCA inflation (4.22%, IBGE, August)
BrentUS$ 96.18−3.5% in the cycle · +6.3% in 30 days
CMO SE/CW · ONSR$ 97.89/MWh≈ US$ 18.8 · +42.9% in the week · yellow tariff flag
CopperUS$ 6.66/lb+0.7% in the cycle · conductors and substations
Infrastructure inputs — 30-day change
Energy and grains rise; battery-chain metals fall. The signal favors those who control dispatch and squeezes those buying long-lead equipment.
30-day change. Source: Brazilian central bank (PTAX, SGS), yfinance, ONS; consolidated on 2026-09-29. Lithium, uranium and critical metals via ETF proxies; iron ore via Vale (VALE3).
Pulse of the five fronts
EnergyTech has the shortest window of the cycle, anchored on the auction date. CleanTech has the longest: what decides there is the funding structure, not a scheduled event.
Decision windows, cycle 2026-09-29
EnergyTech
WINDOW · 30 DAYS
ANEEL approved the tender and confirmed the transmission auction for October 30, 2026, with R$ 8.9 billion in planned investment. Transmission companies that intend to bid need to lock in equipment prices and letters of credit before then. The Mercosur-EFTA agreement — the free-trade deal between the South American bloc and Iceland, Liechtenstein, Norway and Switzerland — enters into force with Iceland on October 1 and with Norway on November 1. It only extends its digital-services rules to providers based in countries whose power mix is at least 67% clean, a bar Brazil clears comfortably. The clause favors data centers located in Brazil and intensifies competition for power purchase agreements (PPAs). The International Energy Agency published an analysis of AI in grid modernization — useful to justify digitalization budgets, but no substitute for physical build-out.
Implied decision
Decide by early October whether the company enters the October 30 auction as bidder, consortium partner or anchor load, and lock in the matching funding.
DeepTech
WINDOW · 60 DAYS
On September 25 Anatel opened public consultations No. 41 and 42/2026, which regulate standard-power outdoor Wi-Fi in the 6 GHz band with automated frequency coordination, with a 70-day comment period. Regional providers gain network capacity without paying for spectrum; router makers need to bring certification forward. Google Cloud announced it will double its infrastructure in Brazil by 2030 and host Gemini data locally, shifting demand for firm power and colocation to Brazilian operators. Gartner projects 49% growth in global AI spending in 2026 — a consultancy forecast, not contracted revenue.
Implied decision
Submit input to consultations 41 and 42/2026 by early December and, in parallel, reserve colocation capacity with contracted power before the next budget cycle.
FinTech
WINDOW · 45 DAYS
The Focus survey lowered its Selic forecast to 13.50% for end-2026, but lenders still price corporate debt in double digits, which delays capital-intensive investment. The Copom minutes explain the cut to 13.75% and provide a basis to renegotiate covenants. Brazil’s central bank and the European Central Bank have begun assessing a link between Pix and TIPS, the euro area’s instant-payment settlement service, and Anatel and the central bank are planning a coordinated block of illegal betting sites involving some 20,000 internet providers and restrictions on Pix.
Implied decision
Review the fundraising schedule under two rate scenarios — the current 13.75% Selic and the projected 13.50% — and appoint a technical owner for betting-block compliance.
CleanTech
WINDOW · 120 DAYS
InPlanet closed non-recourse financing with Idemitsu Americas Holdings for carbon removal through enhanced rock weathering — a structure in which the lender is repaid only from the project’s own cash flow. With a real rate of 9.53% a year, local bank debt remains prohibitive for long-payback climate projects, and foreign-currency funding backed by an offtaker becomes the realistic route. A global manufacturer launched extra-long wind blades to lower the cost per MWh, changing the return curve of projects under design.
Implied decision
Redesign climate-project funding as non-recourse structures backed by international purchase contracts, instead of local bank debt.
AgTech
WINDOW · 45 DAYS
Brazil’s fertilizer agreement with Morocco and the warning of a global food emergency show the input-supply channel under pressure. Corn at 522.25 US¢/bushel and soybeans at 1,297.75 US¢/bushel keep farm margins squeezed, and producers shift investment from heavy machinery to immediate efficiency: soil sensors, targeted spraying and biological inputs.
Implied decision
Diversify fertilizer contracts and focus the precision-agriculture portfolio on solutions that pay back within a single harvest.
Who decides what, next week
The lens translates the cycle’s signals into decisions by function, with a mid-sized company in mind. Each row has a first step that fits in one week.
Link
Observed signal
Recommended decision
First step
Procurement
Data-center demand — Google Cloud plans to double its Brazilian infrastructure by 2030 — intensifies competition for renewable PPAs
Get renewable power supply quotes from at least two suppliers
Request two renewable PPA quotes by Friday
Operations and engineering
Anatel consultations on outdoor 6 GHz Wi-Fi open the way to network capacity without spectrum cost
Map network equipment that can use the new band once released
Inventory Wi-Fi and network gear and check 6 GHz and AFC compatibility
Sales
The 67% clean-energy clause in Mercosur-EFTA, in force with Iceland from Oct 1, favors digital providers based in Brazil
Use Brazil’s power mix as an argument in proposals to EFTA clients
List three clients or prospects in Iceland, Norway or Switzerland
Legal and contracts
Uncertainty over ownership of carbon credits in land-lease contracts
Review ownership clauses before new investments
Send three contracts with carbon credits for review this week
Finance and control
Focus projects a 13.50% Selic for end-2026, versus the current 13.75%
Renegotiate credit lines with clauses that capture the cut, if confirmed
Simulate the debt with the bank under both Selic scenarios
Leadership and partners
The Oct 30 auction and projected rates redefine the timing and cost of capital allocation
Set the priority between contracting power and renegotiating debt this quarter
Convene partners within five days to decide the order
Radar xTech
The complete edition is in the subscriber area
This page summarizes Horizon 1 (0 to 90 days). The subscriber briefing, in Portuguese, extends the reading to 90–360 days and 1–5 years: a pressure map with seven vectors, convergence and international spillover, scenarios by front with triggers, the maturity of 21 technologies, new S-curves and a falsification test of the thesis.
ANEELPower-sector regulator; runs transmission auctions.ONS / CMONational grid operator / its weekly marginal operating cost.Selic / CopomPolicy rate / the central bank’s monetary policy committee.FocusThe central bank’s weekly survey of market forecasts.AnatelTelecom and spectrum regulator.PixThe central bank’s instant-payment system.OiLegacy telecom operator in bankruptcy.Mercosur-EFTATrade deal between Mercosur and Iceland, Liechtenstein, Norway and Switzerland.
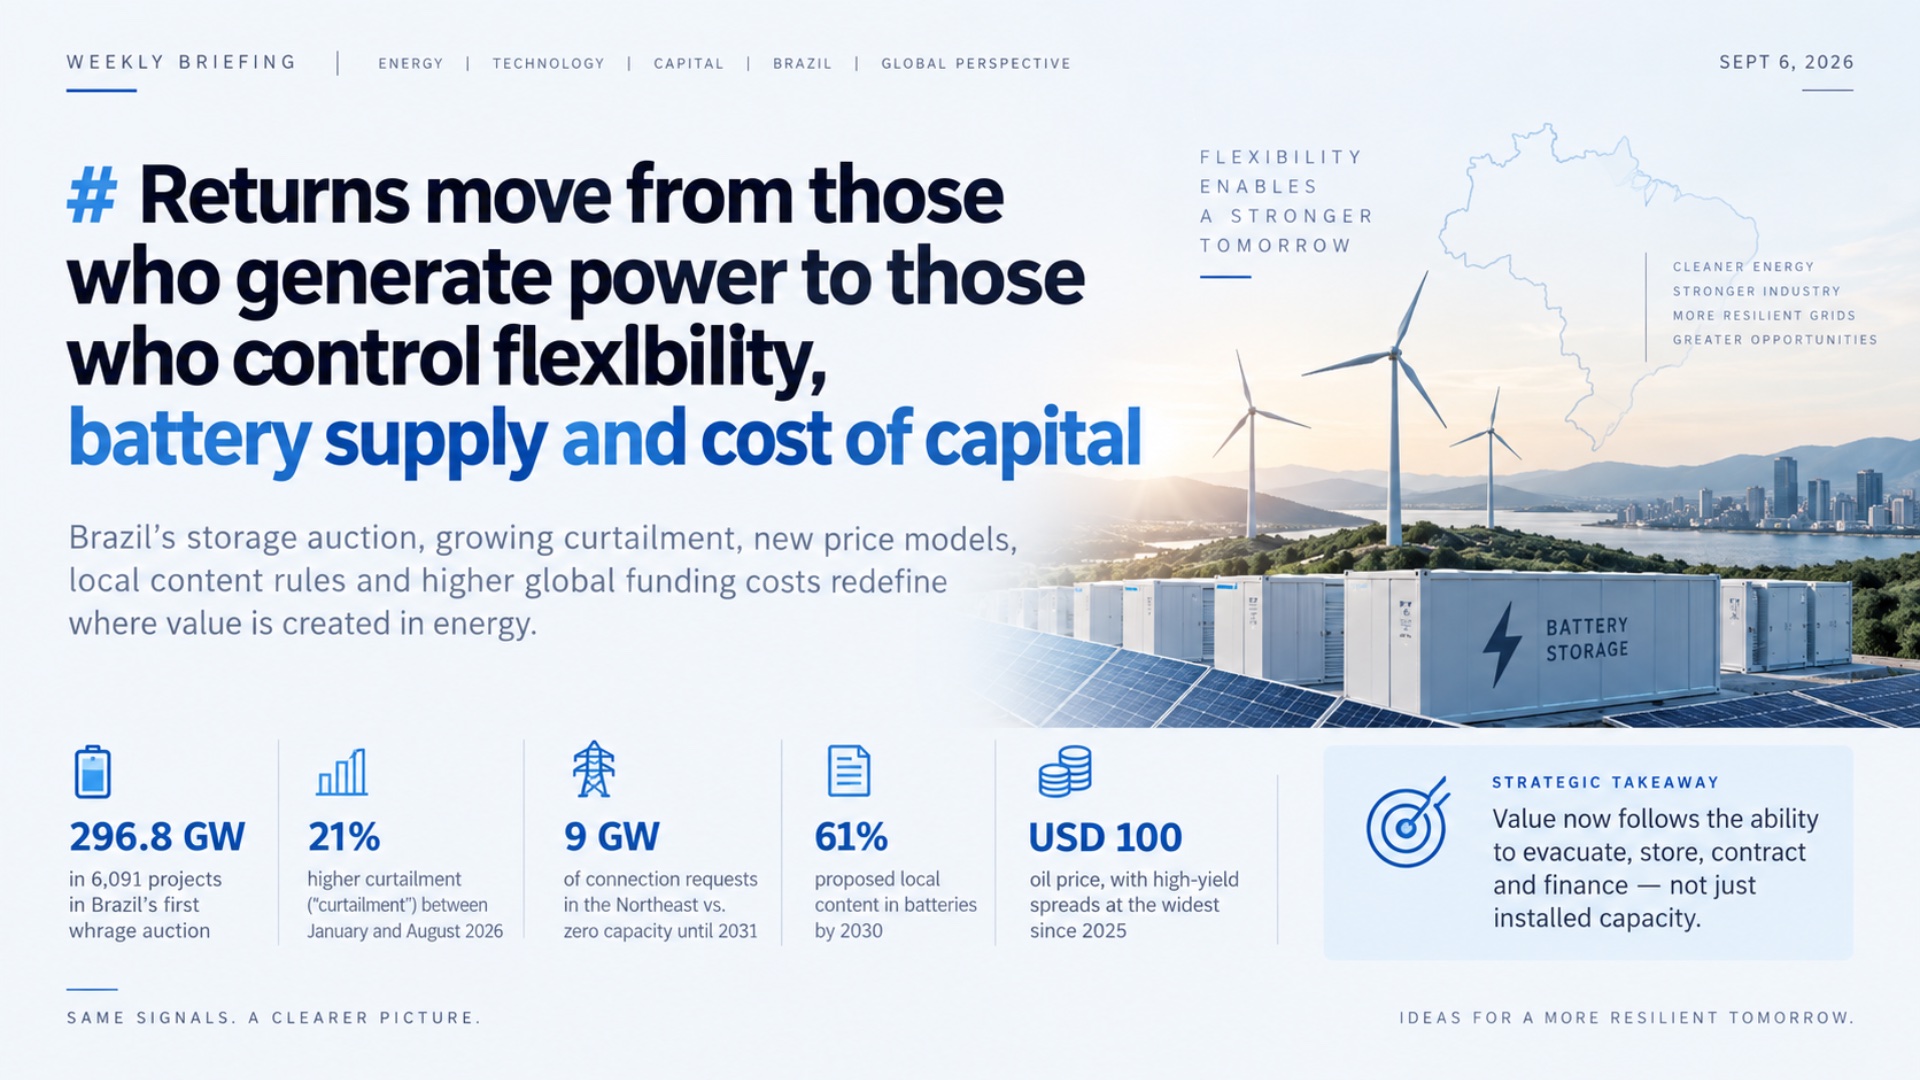
Abstract — Brazil’s first national storage auction drew 296.8 GW across 6,091 registered projects, turning battery storage from an innovation thesis into a capital allocation decision. Curtailment rose 21% between January and August 2026, the national grid operator recorded 9 GW of connection requests in the Northeast against zero remaining capacity until 2031, and on 2 September the market settlement body began applying new Future Cost Functions inside the official models that set the short-term power price. A public consultation on battery local content proposes requirements rising to 61% by 2030. Oil returned to USD 100 and high-yield spreads reached their widest since the 2025 currency crisis. The signals converge on one shift: returns no longer follow installed capacity, they follow control of flexibility, local industrial supply and access to funding.
Why this matters outside Brazil
Supply chain. A local-content requirement rising to 61% by 2030, landing on a market that has just revealed 296.8 GW of storage appetite, forces every global cell and integration business to make a Brazilian manufacturing decision now rather than when the threshold takes effect. A Chinese cell manufacturer has already positioned through a partnership to contest the auction. Whoever waits for the rule to bind will be negotiating from behind.
Capital. Brazil is running, at national scale and ahead of most markets, the experiment of what happens when renewable build-out outruns transmission. Curtailment up 21% in eight months, with zero remaining connection capacity in the country’s best resource region until 2031, is a live preview of a constraint that Chile, Spain, Australia, Texas and India are approaching on their own timelines. The Brazilian repricing of grid access is a leading indicator, not a local curiosity.
Regulatory precedent. Brazil has just conditioned a data-centre tax incentive on the facility being supplied by renewable or low-emission sources. That is one of the first national-scale linkages of fiscal treatment to power sourcing for computing load. Any jurisdiction now drafting data-centre policy will be shown this design, and any operator with a multi-country siting model should assume it can be copied.
Cycle record card
Cycle of 6 September 2026: 1,466 signals processed, 62 sources monitored, 6 countries covered, across five innovation fronts — EnergyTech, CleanTech, DeepTech, FinTech and AgriTech.
Archive in continuous operation since 4 April 2026, with daily collection and weekly consolidation.
Scenario track record: 96 confirmed out of 127 evaluated, with 7.5 days of average lead time and 31 non-materialised.
What changed this week
Theme
Where it stood (31 Aug)
Where it stands (6 Sep)
Direction
Storage
Auction scheduled for December; regional projection of 34 GW by 2035
296.8 GW bid across 6,091 registered projects
Expectation becomes revealed demand
Grid constraint
A single solar park with guarantees at risk over a connection dispute
Systemic figure: curtailment up 21% year to date, 9 GW of requests against nil capacity in the Northeast until 2031
Isolated case becomes structural limit
Price formation
Absent from the previous cycle
New Future Cost Functions applied to the official dispatch models from 2 September
Hedging assumption becomes a variable under revision
Battery supply chain
Not a distinct vector
Local-content consultation proposing up to 61% by 2030, with an Asian cell maker already positioned
Technology theme becomes an industrial decision
Cost of capital
Long US yields at record highs
Consensus survey cuts 2026 growth and raises 2027 inflation; oil at USD 100; high-yield spreads widest since 2025
Approved law conditions the incentive on renewable supply; a level-3 reliability alert abroad flags gigawatt-scale load swings
Incentive becomes technical conditionality
Agriculture and climate
Outside the cycle’s focus
European suspension of Brazilian agricultural imports; warning of a potentially record El Niño
Reputational risk becomes market-access risk
Seven rows, one reading. None of these themes appeared from nowhere. All were already in the archive; what changed this week is their state — the passage from announcement to data, from case to series, from thesis to capital decision.
Executive summary
Theme
Evidence
Tracked since
Strategic impact
Storage
296.8 GW bid across 6,091 projects in the first national storage auction
March 2026
Battery storage stops being an innovation thesis and becomes a board-level capital allocation
Curtailment
Up 21% between January and August 2026
April 2026
Revenue risk for renewable generators moves from price to dispatch
Grid access
9 GW of requests in the Northeast with nil remaining capacity until 2031
July 2026
The scarce asset in an expansion thesis becomes the connection right, not the land or the resource
Price formation
New Future Cost Functions in the official dispatch models from 2 September 2026
September 2026
Price curves underpinning live hedging policies lose validity
Local content
Public consultation proposing battery local content rising to 61% by 2030
September 2026
Integrators must now choose between local manufacturing, joint venture, or loss of incentive access
Tariff subsidy
R$5 billion in northern and north-eastern tariff subsidies frozen by the federal audit court
September 2026
Cash-flow uncertainty for distributors already facing concession risk
Data centres
Law conditions the fiscal incentive on supply from renewable or low-emission sources
August 2026
Power purchase strategy becomes an eligibility prerequisite, not a sustainability initiative
Cost of capital
Oil at USD 100 and high-yield spreads widest since the 2025 currency crisis
June 2026
Securing funding early is now worth more than waiting for a better window
The eight themes describe a single architectural change. Brazil’s power system no longer has a generation quantity problem. It has a coordination problem across four scarcities moving on different clocks: evacuation capacity, contractable flexibility, local industrial supply, and available capital. The storage auction measures the outer boundary of capital appetite. Curtailment measures the cost of not having solved the first scarcity. The local-content consultation defines who participates in the third. Funding conditions decide who can afford to wait. Companies that decide on these four axes separately will reach 2027 holding technically sound assets inside an unviable capital structure.
Reader’s map
Brazilian bodies and regimes referenced in this issue, by function.
Term
What it is
Wholesale settlement body (CCEE)
Settles the wholesale power market and publishes the parameters used to compute the short-term price
Official dispatch models (NEWAVE, DECOMP)
The optimisation models that determine hydrothermal dispatch and, from it, the short-term settlement price. Brazil’s spot price is model-derived, not set by bid-based clearing
Future Cost Functions
The models’ valuation of stored water against future thermal cost. Changing them changes the entire price curve
National grid operator (ONS)
Plans and dispatches the interconnected system; publishes the connection-capacity assessment cited here
Federal audit court (TCU)
Audits federal spending and can suspend budget execution, including subsidy transfers
Energy Reallocation Mechanism (MRE)
Pools hydro output and shares generation risk among participating plants; under review for 2027
Basic Productive Process (PPB)
The local-content regime that conditions tax benefits on performing specified manufacturing steps inside Brazil
Data-centre incentive regime
Recently approved tax regime conditioning benefits on renewable or low-emission power supply
Consensus forecast survey
The central bank’s weekly compilation of market economists’ macro projections
Instant payments and open banking (Pix, Open Finance)
The central bank’s instant payment rail and data-sharing framework, now the main competitive vector in Brazilian credit
Power
Revenue risk moves from price to dispatch
Curtailment rose 21% over the first eight months of 2026, and the grid operator’s connection-capacity assessment recorded 9 GW of generator requests in the Northeast against nil remaining capacity until 2031. The relevant reading is not the percentage; it is the change in the nature of the risk. A renewable generator has historically hedged against price by indexing contracts and buying financial cover. When the binding constraint becomes physical, a contract indexed to generated volume stops being protection and becomes exposure, because energy that cannot be evacuated earns nothing regardless of the agreed price. The transmission channel here is supply: the constraint acts on quantity delivered, not on unit value. Long-term contracts signed on full-evacuation assumptions need to be reopened and repriced before the exposure lands in 2027 results.
The price curve that supported the hedge has stopped being valid
On 2 September 2026 the wholesale settlement body began applying new Future Cost Functions inside the official dispatch models, altering how the short-term settlement price is formed. This is the point most easily missed from outside Brazil. The Brazilian spot price is not the outcome of bid-based clearing; it is computed by optimisation models that value stored hydro against expected future thermal cost. Changing those functions is therefore not a technical footnote with deferred effect. It immediately invalidates the internal curves used to size hedge positions, calculate portfolio exposure and project trading revenue. The channel is regulatory and the response window is short, because 2027 budget approval is already on most boards’ calendars. Add the review of the hydro risk-pooling mechanism and of curtailment compensation rules for 2027, which reaches 33 GW of distributed generation facing technical adaptation, and a meteorological warning of a potentially record El Niño adding hydrological risk to the same window. Three independent variables converging on one quarter produce a risk that none of them produces alone.
Battery supply chain
The auction measured appetite; the consultation decides who participates
296.8 GW across 6,091 registered projects says that the entry barrier to storage in Brazil has stopped being technological. It has become regulatory qualification and cost of capital. In parallel, the federal public consultation on the local-content regime for batteries used in storage, electric vehicles and distributed systems proposes requirements rising to 61% by 2030. The two facts must be read together. The auction sets the size of the market; the local-content rule sets who reaches it with incentive support. Any integrator now faces a three-way decision with a deadline defined by the consultation itself: local assembly, joint venture with a foreign manufacturer, or remaining an importer without access to the benefit. The entry of an Asian cell manufacturer through a partnership to contest the auction indicates that the winner of localisation will be whoever builds industrial operations before the threshold binds, not whoever imports cells once it does.
The US import ban arrives through price, with the timing inverted
The executive order banning imports of inverters, transformers and power equipment into the United States acts on the Brazilian market in two opposite tempos. In the short term, manufacturers shut out of the US redirect volume, which tends to compress equipment prices in Brazil. Over the medium term, that same redirection compromises warranties, technical support and continuity of supply, because a manufacturer that loses its principal market restructures its service footprint. The channel is supply and price simultaneously, and the trap is in the sequence: the advantage arrives first and the liability later. Procurement decisions taken on acquisition price alone over the next two quarters may lock in a materially higher lifecycle cost.
Digital infrastructure
A data-centre tax incentive has become an energy clause
Brazil’s Senate approved the fiscal regime conditioning data-centre incentives on electricity demand being met by renewable or low-emission sources. This converts power procurement into an eligibility prerequisite rather than a corporate sustainability initiative. The channel is regulatory and the effect on financial modelling is immediate: for any project depending on the incentive, the power purchase agreement moves onto the critical path of approval rather than into a later cost-optimisation phase. Continuing legislative instability around the regime adds execution risk, which argues for dual contingency — legal and supply — regardless of the outcome.
The next constraint is technical, and it has already been signalled abroad
The level-3 reliability alert issued by the North American reliability body, prompted by gigawatt-scale load fluctuations from AI data centres, previews with reasonable clarity what the Brazilian operator will require of the very projects the new law incentivises: ramp requirements and contracted demand response. There is an under-exploited locational opportunity here. Flexible computing load sited near constrained generation captures energy that is currently curtailed, converting a system liability into a low-cost input. It is the only reading in this cycle where curtailment appears as an asset rather than a loss. In parallel, active exploitation of a remote code execution vulnerability across all Chromium versions reaches remote-access workstations for industrial control systems in energy and telecoms, and the bankruptcy of a major Brazilian carrier exposes network service suppliers to material counterparty risk. The data protection authority’s announcement of a dedicated AI regulatory sandbox signals that model supervision will have its own technical counterpart, and that participating is likely to be a lower-friction path than litigating later.
Capital
The cost of waiting rose faster than the cost of being early
The consensus forecast survey published on 31 August cut 2026 growth and raised 2027 inflation expectations, a combination that lifts the discount rate applied to long-dated infrastructure. Oil returned to USD 100 per barrel after military escalation in the Strait of Hormuz beginning 1 September, reopening pass-through into fuels and into contractual indexation. US diesel reached USD 5.85 per gallon on 4 September, above the 2022 record. High-yield spreads reached their widest since the 2025 currency crisis, directly raising the cost of external funding for Brazilian energy and infrastructure issuers. The channel is credit, and it operates by selection: projects with contracted revenue and strong counterparties get through; projects on merchant revenue with uncertain regulatory timelines do not. The practical implication is counterintuitive for anyone trained to wait for the best window. When the cost of capital rises for structural rather than cyclical reasons, bringing forward funding planned for 2027 tends to be worth more than optimising the coupon.
Brazil’s domestic financial infrastructure is moving the other way
While external funding grows expensive, domestic payments infrastructure is maturing: open banking lowering credit costs, portability advancing, marketplaces competing with incumbent banks for origination, and meaningful consolidation in digital assets. Corporate credit cases in the power sector reaching indices and portfolios show that sector regulatory risk now transmits directly into financial markets. For infrastructure treasuries this opens a concrete alternative: part of the funding that became expensive in hard currency can migrate to domestic structures that did not carry this liquidity two years ago.
Agriculture, climate and trade
Export margin now depends on compliance, not on volume
The European Union confirmed the suspension of Brazilian agricultural imports, a shock that moves traceability and environmental compliance from the reputational plane to the market-access plane. Add the warning of a potentially record El Niño, which threatens productivity and forces a review of harvest assumptions and climate insurance cover, and global pressure on distillates, which reaches Brazilian agribusiness through freight and machinery operating costs. The three fronts converge on the same operational conclusion: next season’s export margin will depend on documentary compliance, fuel hedging and agronomic resilience, not on volume produced.
Consolidated decision matrix
Priority
Recommended action
Horizon
High
Reprocess internal price curves using the Future Cost Functions in force since 2 September
30 days
High
Reclassify curtailment-exposed contracts in the risk committee before closing the 2027 budget
30 days
High
Hedge diesel and fuel exposure against oil at USD 100 and record distillate prices
30 days
High
Fix the board’s position in the battery local-content consultation: local manufacturing, joint venture, or import without incentive
Consultation deadline
High
Bring forward funding planned for the first half of 2027
60 days
High
Set a closed remediation deadline for the browser vulnerability on terminals with access to control environments
15 days
High
Structure data-centre incentive eligibility through a renewable PPA and contracted demand response
60 days
Medium
Re-present investment cases to the board with WACC recalculated on the revised curve
90 days
Medium
Prioritise renegotiation of transmission contracts and hydro pooling terms before the 2027 rules consolidate
90 days
Medium
Evaluate co-location of flexible load next to constrained generation
90 days
Medium
Map contractual exposure to frozen tariff subsidies and review rebalancing clauses
90 days
Medium
Re-test agricultural productivity assumptions under a severe El Niño before planting
Before season
Medium
Assess partial migration of external funding into domestic structures
120 days
Low
Structure local battery manufacturing partnerships for the 2030 horizon
180 days
Cross-front convergence
The cycle’s anchor signal — the volume bid into the storage auction — is not a sector event. It reaches all five monitored fronts with different urgencies, and that asymmetry is what determines where attention goes first.
Front
Effect
Urgency
EnergyTech
Confirms storage as a board-level capital decision and accelerates the sector investment curve
Immediate
FinTech
The change in price-formation methodology invalidates curves used in hedging and creates repricing risk on live instruments
Immediate
DeepTech
Auction scale creates concrete demand for cell chemistry, dispatch software and portfolio optimisation
Immediate
CleanTech
Strengthens the viability of intermittent sources by addressing firmness, though the effect on targets depends on execution by auction winners
Medium term
AgriTech
May benefit irrigation and electrified rural operations, with impact still indirect and unconfirmed this cycle
Monitor
An event on one front is news. An event that connects several is a structural vector. The difference between the two readings is not in the event. It is in having all five fronts under observation, at the same time, with the same method.
Scenarios and triggers
A scenario is not a point forecast. It is a structured hypothesis under uncertainty, with a revisable probability and a declared confirmation trigger. The metric that matters is lead time and calibration, not the percentage of futures guessed correctly.
Scenario
Type
Confirmation trigger
In formation
Regulatory fragmentation and scarce capital
Risk
Rising litigation over grid use and connection lengthening average licensing time
25 days
Regulatory paralysis under demand pressure
Risk
Undefined connection rules deterring capital despite proven demand
6 days
Fast regulatory framework with a digital boom
Opportunity
Regulatory acceleration creating predictability for storage and smart grid
6 days, no confirming signal yet
Gradual adjustment in a mixed environment
Mixed
Partial regulatory progress allowing value capture in niches such as bilateral flexibility contracts
30 days
For the power sector specifically, the base-case scenario in formation assumes partial conversion of auction bids into contracted projects, concentrated in short-duration batteries with local content still nascent. Its declared trigger is publication of results with contracted volume between 10% and 20% of the total bid. The upside case requires an announced industrial battery investment with local content above 40%. The downside confirms if the transmission auctions scheduled for the period are postponed or draw weak participation.
Radar scorecard
Of 127 scenarios evaluated since operations began, 96 confirmed, with an average lead time of 7.5 days between issue and event. Thirty-one did not materialise within their stated window.
Among recent confirmations, lead times ranged from 1 to 13 days. “Grid and batteries converge on AI” confirmed at 7 days. “Asymmetric expansion under unstable rules” confirmed at 9. “Broad opening without a storage base” confirmed at 13. By contrast, “Gradual advance with uneven resilience” registered only a partial signal and did not reach the confirmation threshold before its deadline, even though signal volume ran 153% above its mean — a case in which intensity of attention did not convert into outcome, and which remains in the archive as non-materialised.
Strategic synthesis
The transformation under way is not the isolated rise of batteries, of data centres or of renewable generation. It is the passage from a system in which returns followed installed capacity to one in which returns follow the ability to evacuate, store, contract and finance. Curtailment makes the shift visible, because it demonstrates that available megawatts can carry reduced marginal value when the grid cannot absorb them. The storage auction shows that capital has already understood this and moved ahead of regulation. The local-content consultation shows the state will respond through industrial policy. Funding conditions show the window for responding is not open indefinitely.
Those positioned to gain are holders of contractable flexibility, participants who secure a position in the local battery chain before the content threshold binds, owners of guaranteed connection outside congested regions, and issuers who bring funding forward while appetite remains. Those positioned to lose are standalone renewable assets in congested regions, projects with revenue indexed to generated volume and no protection against dispatch, integrators betting on pure imports, and companies dependent on external funding in a widened spread market.
The competitive capability that now decides is coordination. Not choosing the best technology, nor achieving the lowest unit cost, but the ability to decide simultaneously across four clocks that are not synchronised: the physical clock of the grid, the regulatory clock of price formation and local content, the industrial clock of the supply chain, and the financial clock of the funding window. A board that treats these as four separate agenda items, each in its own committee and its own quarter, will reach 2027 holding technically sound assets inside an unviable capital structure.
The cost of inaction is asymmetric. Waiting for regulatory clarity reduces uncertainty but eliminates access to the best connection points, the best funding terms and the industrial partnerships still available. The answer is not to choose between waiting and investing indiscriminately. It is to build optionality: secure connection, negotiate conditional contracts, reserve equipment, prepare funding and structure industrial partnership ahead of full capital commitment.
Questions for the board
Strategic question
Purpose
Have our internal price curves already been reprocessed with the Future Cost Functions in force since 2 September, or is the 2027 budget being built on revoked assumptions?
Verify the revenue assumption still exists
What share of the portfolio remains viable if curtailment stops being an exception and becomes a permanent assumption?
Separate price exposure from dispatch exposure
What is our stated position in the battery local-content consultation, and who on the board owns it?
Force the industrial decision inside the regulatory deadline
If the data-centre incentive depends on renewable supply, is our PPA on the project’s critical path or in the optimisation phase?
Reposition power procurement as a prerequisite
Are we optimising the coupon on 2027 funding in an environment where the cost of waiting has already exceeded the cost of acting early?
Test funding timing discipline
Can our governance decide jointly on grid, regulation, supply chain and capital, or do those four decisions run in separate committees and separate quarters?
Assess whether structure matches convergence
Methodology note
This briefing is the weekly consolidation of an archive in continuous operation since April 2026, with daily collection across dozens of public sources spanning regulatory agencies, system operators, specialist sector press, technical publications and international market data providers. Each cycle scores, classifies and cross-references signals across five fronts, and records scenarios with a declared confirmation trigger and deadline whose outcome is audited afterwards and published, non-materialised cases included.
What distinguishes this reading from a sector summary is the series. An isolated signal is news; the same variable measured across twenty-two weeks shows acceleration, stabilisation or reversal, and that is what makes it possible to say a theme ran 72% above its own mean before it became a headline. Isolated sector feeds cannot capture this, because they do not talk to each other: the effect of an energy event on financial instruments, or of a local-content rule on applied research, appears only when the fronts are observed with one method inside one cycle.
Cookie Consent
Usamos cookies essenciais para o funcionamento do site e, com a sua autorização, cookies de estatística e marketing para entender o uso e melhorar o conteúdo. Você pode aceitar, recusar ou escolher por categoria.
Escolha abaixo quais categorias de cookies você autoriza. Os essenciais não podem ser desativados.
Cookies essenciais permitem funções básicas, a segurança e o registro das suas escolhas de consentimento. São necessários para o funcionamento do site e não podem ser desativados.
Nome
Descrição
Duração
Preferências de cookies
Armazena as escolhas de consentimento de cookies do visitante.
30 dias
Cookies de estatística nos ajudam a entender, de forma agregada, como os visitantes usam o site, para melhorar o conteúdo. Só são ativados com a sua autorização.
Ferramenta do Google que mede e analisa o tráfego do site, como páginas visitadas e origem das visitas, para orientar decisões editoriais.
Monitora o número de requisições ao servidor do Google Analytics quando o Google Tag Manager é usado.
1 minuto
__utma
Identificador usado para distinguir usuários e sessões.
2 anos após a última atividade
__utmt
Monitora o número de requisições ao servidor do Google Analytics.
10 minutos
__utmb
Distingue novas sessões e visitas. É criado quando a biblioteca GA.js é carregada e atualizado a cada envio de dados ao Google Analytics.
30 minutos após a última atividade
__utmc
Usado apenas por versões antigas (Urchin) do Google Analytics para distinguir novas sessões e visitas ao fim de uma sessão.
Fim da sessão do navegador
__utmz
Registra a origem do tráfego ou a campanha que trouxe o visitante ao site. É atualizado a cada envio de dados ao Google Analytics.
6 meses após a última atividade
__utmv
Armazena informações personalizadas definidas pelo desenvolvedor no Google Analytics. É atualizado a cada envio de dados.
2 anos após a última atividade
__utmx
Indica se o visitante participa de um teste A/B ou multivariado.
18 meses
_ga
Identificador usado para distinguir usuários.
2 anos
_gali
Usado pelo Google Analytics para identificar quais links da página são clicados.
30 segundos
_ga_
Identificador usado para distinguir usuários e manter o estado da sessão.
2 anos
_gid
Identificador usado para distinguir usuários por 24 horas após a última atividade.
24 horas
_gac_
Contém informações sobre campanhas de marketing, compartilhadas com o Google Ads quando as contas do Google Ads e do Google Analytics estão vinculadas.
90 dias
Estatísticas de visitantes do Jetpack: registram visualizações de página, sites de origem, termos de busca e cliques em links externos.